International equities – October 2026
The information in these articles is current as of 1 October 2026.
Overview
International equities delivered a mixed start to FY27, returning 1.5% over the September quarter and 9.9% over the 12 months to 30 September. Currency movements remained a significant headwind for Australian investors, with the Australian dollar appreciating strongly. The RBA’s trade-weighted index rose almost 8% over the year, resulting in hedged international equities returning 16.3%, materially outperforming their unhedged counterparts by 6.5 percentage points.
Market performance over the past year was highly concentrated, with only the Technology, Health Care and Energy sectors outperforming the benchmark. Elevated energy prices and higher interest rate expectations weighed on more economically sensitive areas of the market, particularly Consumer Discretionary, which underperformed the broader index by 21%.
MSCI World ex Australia Cumulative total return (Sep-25 to Sep-26)
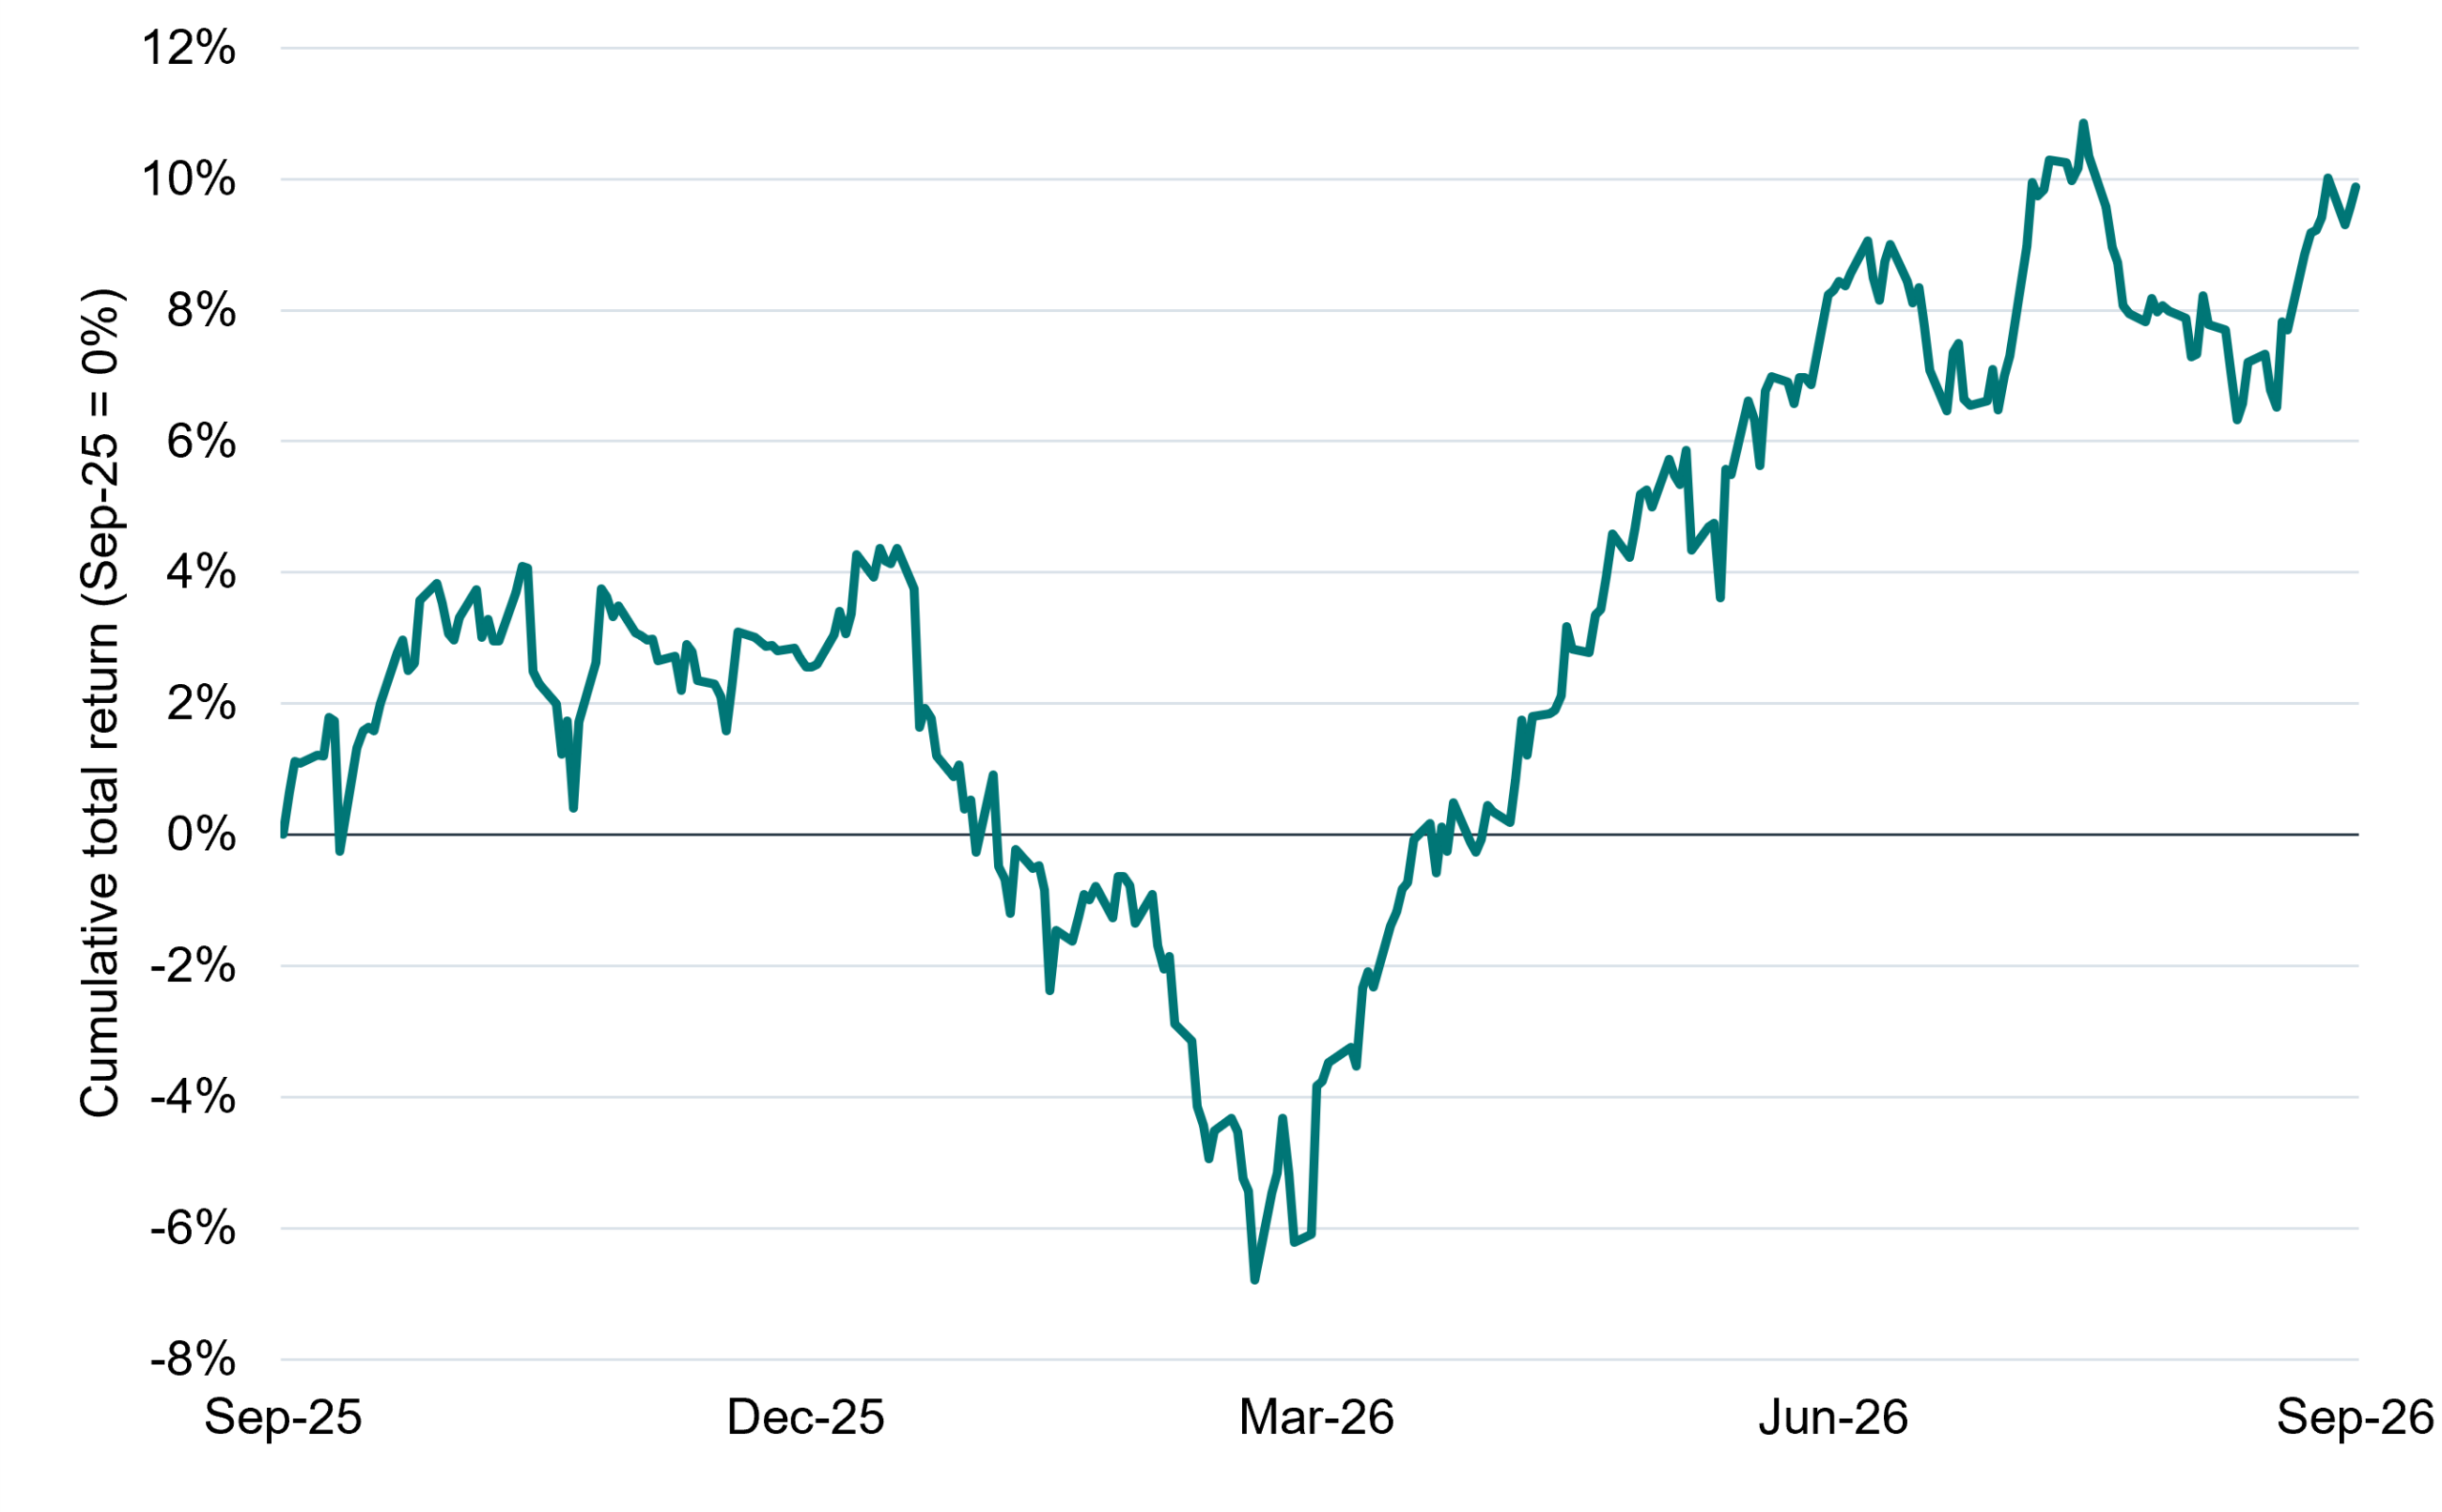
Source: Bloomberg, PPSPW calculations.
Outlook
The narrative surrounding Artificial Intelligence (AI) took a major turn in the September quarter as investor concerns intensified.
The first concern centred on the sustainability of AI-related capital expenditure. The industry’s buildout continues at an extraordinary pace, requiring hundreds of billions of dollars for advanced chips, data centres and supporting infrastructure. An estimated US$262 billion of debt funding is being raised in 2026 alone, with a further US$420 billion forecast for 2027[1]. As a result, free cash flow has come under pressure across much of the technology sector, with Microsoft remaining a notable exception as many industry leaders prioritise growth over near-term cash generation.
The second factor is the growing calls for a “slowdown” in AI advancement from industry leaders in OpenAI and Anthropic[2]. These leaders worry about the potential for AI to cause significant societal harm and advocated a position of introducing more safeguards to manage development. This weighed on sentiment as investors feared that tighter regulation could ultimately moderate the pace of AI-related investment and spending.
Ultimately, we see these factors as transient. Earnings outcomes for major tech companies will dictate the pace of AI-related spending. Amazon’s AWS division saw revenue growth accelerate to US$200bn, up 37% for the year to June[3] with Alphabet and Microsoft similarly seeing material expansion. The launch of new consumer-focused AI products, including Meta’s Muse, highlights the broadening range of monetisation opportunities extending beyond traditional cloud infrastructure.
We also see little prospect of a meaningful industry-wide retrenchment in AI spending. Competition among major US technology firms, alongside rapidly advancing Chinese developers, continues to create strong incentives for ongoing investment and research. Regulatory restrictions on certain Chinese-developed AI models may emerge on national security grounds, but these are more likely to influence competitive positioning than materially slow overall industry development.
Finally, the global economy has navigated energy market volatility surprisingly well. There are signs that traffic is getting through the Strait of Hormuz to a significant extent. Global industrial production is sitting above its long-term average while global trade, in aggregate, has also improved in recent months as the tariff volatility from last year winds down. Inflation is a concern with central banks responding to higher energy prices with rate hikes raising financing costs and pressuring discount rates. That said, higher inflation is also coinciding with strong overall growth. This combination whilst not ideal is still a net positive for equities as the risk of an outright contraction in profits should continue to be low in the near term.
In summary, we believe concerns surrounding AI capital expenditure are overstating the risks relative to the scale of the opportunity. AI adoption continues to support strong revenue growth across key beneficiaries, while the broader economic backdrop remains supportive of corporate profitability.
Valuations
The US market remains expensive relative to its long-term history. However, strong earnings growth, favourable near-term prospects, and improving business quality arguably help justify this premium. While valuations may present a modest headwind, they are not sufficiently stretched to warrant a materially negative view.
Elsewhere, opportunities remain more balanced, with a mix of attractive entry points and only modest valuation pressures. Australia stands out as one of the more expensive markets globally, a premium that appears difficult to justify given its relatively subdued growth outlook and sector composition.
| Region | Forward P/E Ratio (FY28) | 20-year Median 20-year Forward PE ratio | Potential upside/downside |
| USA | 15.9x | 14.6x | -7.6% |
| All Country World (ex-US) | 11.1x | 11.6x | +4.7% |
| Australia | 15.8x | 14.0x | -11.9% |
| Europe | 12.8x | 12.2x | -4.3% |
| Emerging markets | 8.1x | 9.7x | +20.5% |
| Japan | 14.3x | 13.1x | -8.5% |
| UK | 11.6x | 11.3x | -2.3% |
| China | 8.6x | 9.2x | +7.9% |
Source: Bloomberg, PPSPW calculations.
Conclusion
Recommendation: Remain overweight.
Artificial intelligence remains a potent force driving global earnings growth. While concerns around the sustainability of AI-related investment have weighed on valuations, particularly across semiconductor companies in South Korea and the United States, underlying growth trends remain robust in our view.
More importantly, the global economic backdrop remains supportive. Key indicators such as industrial production and trade volumes continue to trend positively, underpinning ongoing profit growth. While tensions in the Middle East remain a risk, efforts to mitigate disruptions to energy supply routes have so far proven effective.
Although valuations across global developed markets are not cheap, conditions remain favourable for further earnings expansion. We therefore continue to believe that an overweight allocation to equities is warranted.
[1] G. Chavez-Dreyfuss, ‘Corporate bond buyers get picky with flood of AI debt’, Reuters (22 September 2026), Corporate bond buyers get picky with flood of AI debt | Reuters, (accessed 23 September 2026).
[2] “Anthropic boss Dario Amodei calls for AI development to slow down”, BBC, 12 September 2026: Anthropic boss Dario Amodei calls for AI development to slow down
[3] “Amazon Q2 2026 earnings, AWS grows 37%, revenue tops $200B”, yahoo!finance, 31 July 2026: Amazon Q2 2026 earnings: AWS grows 37%, revenue tops $200B